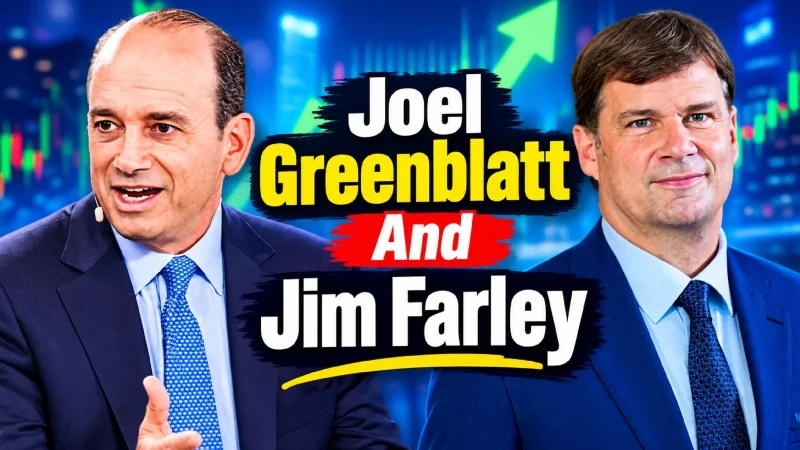
Joel Greenblatt and Jim Farley operate in different areas of the business world, yet their careers offer an interesting way to examine how companies create long-term value. Greenblatt is an investor, author, and professor known for his disciplined approach to identifying attractive businesses. Farley is an automotive executive known for leading Ford Motor Company through a period of technological change, intense competition, and shifting customer expectations.
Although Joel Greenblatt and Jim Farley have different professional backgrounds, both provide useful perspectives on a central business question: what makes a company valuable over time?
For investors, that question often involves profitability, valuation, competitive advantages, and management quality. For corporate leaders, it involves product development, operational efficiency, customer relationships, and the ability to adapt when an industry changes.
Their careers are not evidence of a direct professional partnership or shared investment strategy. Instead, examining their respective approaches reveals how financial analysis and operational leadership can contribute to a broader understanding of business performance.
Who Is Joel Greenblatt?
Joel Greenblatt is an American investor, author, and academic widely associated with value investing. He is known for explaining investment principles in practical terms, particularly the importance of purchasing strong businesses at attractive prices.
Greenblatt has been associated with Gotham Capital, an investment firm he founded, and has written influential books about investing. His best-known works include The Little Book That Beats the Market and You Can Be a Stock Market Genius.
Rather than relying entirely on market predictions or short-term price movements, Greenblatt’s investment philosophy emphasizes analyzing the economics of individual businesses.
Understanding the Magic Formula
One of Greenblatt’s best-known contributions to investing is the Magic Formula, a systematic method for identifying potentially attractive stocks.
The approach combines two important characteristics:
- Return on capital: An indication of how efficiently a company uses its capital to generate operating profits.
- Earnings yield: A valuation measure that helps investors assess the earnings a business produces relative to its market price, using Greenblatt’s preferred formula.
The underlying idea is straightforward: investors should look for businesses that generate strong operating returns while trading at reasonable valuations.
A company with excellent profitability may still be a poor investment if its stock price already reflects unrealistic expectations. Conversely, a low-priced stock may be inexpensive for good reasons, including declining demand, excessive debt, or weakening competitive advantages.
Greenblatt’s framework encourages investors to evaluate business quality and price together.
Why Business Quality Matters
A company’s financial results are more informative when investors understand how those results are produced.
Consider two hypothetical manufacturers. The first generates substantial operating profits using relatively little capital. The second earns similar profits but requires significantly more investment in factories, equipment, and working capital.
Even if their current earnings look comparable, the first business may have more attractive economics, depending on its growth opportunities, risks, and capital requirements.
This illustrates why investors examine capital efficiency instead of focusing exclusively on revenue or earnings growth.
However, financial ratios should not be treated as automatic buy signals. Accounting differences, cyclical demand, unusual earnings, and industry-specific capital requirements can make direct comparisons misleading.
Greenblatt’s approach is best understood as a screening framework that helps investors identify businesses for deeper research, not as a guarantee of investment success.
Who Is Jim Farley?
Jim Farley, whose full name is James D. Farley Jr., is the president and chief executive officer of Ford Motor Company. He became CEO in October 2020 after holding senior positions at Ford and working in the automotive industry at Toyota and Lexus.
Farley’s career has centered on understanding customers, building competitive vehicle brands, and managing a complex global manufacturing business. His responsibilities involve decisions that extend far beyond vehicle design, including production costs, supply chains, technology, workforce management, and capital allocation.
Leading Ford Through Industry Change
The automotive industry faces several overlapping challenges. Automakers must respond to changing consumer preferences, rising technology costs, electric vehicle development, software innovation, and competition from established manufacturers and newer entrants.
Under Farley’s leadership, Ford introduced the Ford+ strategy, which emphasized customer-focused growth, improved business performance, and a more focused approach to its different operations. The company organized its automotive business around Ford Blue, Ford Model e, and Ford Pro to distinguish its traditional gas and hybrid vehicle operations, electric vehicle development, and commercial vehicle business.
This structure reflects an important management principle: different products and customer groups may require different operating priorities.
For example, commercial customers often prioritize vehicle uptime, durability, service availability, and operating costs. Electric vehicle buyers may place greater emphasis on range, charging access, battery performance, and purchase incentives. A company serving both groups must understand these differences rather than assume a single strategy will work equally well for everyone.
Why Execution Matters More Than Announcements
An executive can announce a promising strategy, but the results depend on implementation.
In the automotive industry, execution involves coordinating engineering teams, factories, suppliers, dealerships, software developers, and service networks. Delays or cost overruns in one area can affect the performance of an entire product line.
For investors, this distinction is important. A company’s strategic ambitions do not necessarily translate into sustainable profits or attractive shareholder returns.
A useful evaluation of Ford therefore considers its actual financial performance, product competitiveness, cash flow, capital spending, and ability to manage costs alongside management’s stated objectives.
Farley’s role illustrates the operational side of business value: executives must turn resources and strategic decisions into products and services that customers are willing to buy.
Are Joel Greenblatt and Jim Farley Connected?
The key distinction is between a direct personal or professional relationship and a potential connection through business or investment activity.
Greenblatt is known primarily for investment management and value investing, while Farley is known for automotive leadership. Their careers are separate, and any claim that they are partners, close associates, or collaborators requires specific supporting evidence.
However, there is a meaningful way to examine their names together: the relationship between investing in a company and managing that company.
An investor evaluates whether a business is worth buying at its current share price. An executive makes decisions that influence the business’s operating results, competitive position, and future prospects.
These roles intersect economically, even when the individuals involved have no direct relationship.
A further distinction matters when discussing Ford stock. Gotham Asset Management’s reported investment holdings can provide information about the firm’s exposure to publicly traded companies, but a fund’s holdings should not automatically be described as Greenblatt’s personal investments or endorsements. Any specific claim about Gotham’s Ford position needs to be tied to a dated regulatory filing and interpreted in context.
What Investors Can Learn From Greenblatt’s Approach to Ford
Applying Greenblatt’s investment principles to a company such as Ford provides a practical example of how valuation and corporate strategy interact. This is an analytical exercise, not a claim that Greenblatt has publicly endorsed Farley’s leadership or that the two have a direct working relationship.
Ford is an established automaker with recognizable brands, a substantial manufacturing footprint, commercial vehicle operations, and a long history in the American automotive market. At the same time, it faces capital-intensive production requirements, competitive pricing pressures, and the challenge of investing in new technologies while maintaining profitability in existing businesses.
These factors make it important to examine several dimensions of the business.
1. Profitability and Return on Capital
An investor can start by examining how effectively Ford converts its resources into operating earnings.
Relevant measures include operating margins, return on invested capital, and segment-level profitability. Comparing these measures over several years can help reveal whether improvements are sustainable or reflect temporary conditions.
Automotive manufacturers require substantial investment in factories, tooling, research, and equipment. As a result, strong revenue growth does not necessarily mean that a company is generating attractive returns on the capital it commits.
2. Valuation and the Price of Shares
A business can have a recognizable brand and experienced management while still being an unattractive investment at a particular price.
Investors need to compare the company’s expected earnings and cash flows with its market valuation. They should also consider debt, pension obligations, capital expenditures, and the cyclical nature of automotive demand.
A low price-to-earnings ratio, for example, does not automatically indicate that a stock is undervalued. The market may be anticipating lower future earnings or additional financial challenges.
Greenblatt’s framework reinforces the importance of examining price alongside business economics rather than treating either factor in isolation.
3. Capital Allocation and Strategic Priorities
Farley’s executive decisions influence how Ford allocates capital among vehicle development, manufacturing improvements, electric vehicles, software, and commercial services.
Investors can evaluate these decisions by asking whether spending priorities match customer demand and whether the resulting products and services generate sufficient economic returns.
A major investment may be strategically necessary without producing attractive short-term financial results. Conversely, cutting investment may improve near-term cash flow while weakening a company’s competitive position over time.
The key is to evaluate both the financial consequences and the long-term rationale behind management’s choices.
4. Competitive Advantages and Business Risks
Brand recognition, dealer relationships, manufacturing expertise, and established commercial customers can support an automaker’s competitive position. However, these advantages do not eliminate competition.
Changes in consumer preferences, technological development, production costs, and pricing can affect future performance.
Investors should therefore distinguish between a company’s established strengths and the assumptions required for those strengths to remain valuable.
How Corporate Leaders and Investors View Business Value Differently
The careers of Joel Greenblatt and Jim Farley illustrate two complementary perspectives on business performance.
| Area | Investor’s perspective | Executive’s perspective |
|---|---|---|
| Profitability | Is the business generating attractive returns? | How can operations improve earnings? |
| Capital allocation | Is the company using capital efficiently? | Where should resources be invested? |
| Competition | Does the company have durable advantages? | How can the company defend or strengthen those advantages? |
| Risk | What could undermine the investment case? | What operational and strategic risks must be managed? |
| Valuation | Is the stock price attractive relative to fundamentals? | How can management strengthen the underlying business? |
| Time horizon | Will expected returns justify the investment? | Will today’s decisions improve future performance? |
The distinction is important because business quality and investment attractiveness are related but separate concepts.
An executive may make sound operational decisions while the company’s shares remain expensive. Likewise, a stock may trade at a low valuation even when its business faces substantial challenges.
A thorough analysis considers both perspectives without assuming that one automatically guarantees the other.
Practical Lessons for Business Owners and Individual Investors
The comparison also offers useful lessons beyond the automotive industry.
Focus on Measurable Results
Business plans should be evaluated against actual outcomes. Revenue, operating margins, cash flow, customer retention, and capital efficiency can help determine whether a strategy is working.
The appropriate measures depend on the business, but they should connect management decisions with economic results.
Separate a Good Company From a Good Investment
Investors sometimes become attached to familiar brands or admired executives. However, a company’s reputation cannot replace financial analysis.
Before investing, consider what the current share price already assumes about future growth, profitability, and risk.
Understand the Business Before Comparing Its Numbers
Financial ratios are useful only when interpreted in context. A software company, an industrial manufacturer, and an automaker have different capital requirements and economic characteristics.
Comparisons should account for those differences rather than rely on a single metric.
Be Patient but Remain Willing to Reassess
Long-term strategies often require time, but patience should not mean ignoring new evidence.
Investors should revisit their assumptions when financial results, competitive conditions, or management decisions change. Executives must also adjust their plans when customer needs or market conditions shift.
Frequently Asked Questions
1. Who are Joel Greenblatt and Jim Farley?
Joel Greenblatt is an American investor, author Joel Greenblatt and Jim Farley, and academic known for value investing and the Magic Formula. Jim Farley is the president and CEO of Ford Motor Company, with a career in automotive management and leadership.
2. Are Joel Greenblatt and Jim Farley business partners?
Their careers are associated with different professional fields: investment management and automotive leadership. A direct business partnership should not be assumed without reliable documentation establishing one.
3. What is Joel Greenblatt best known for?
Greenblatt is best known for his value-investing philosophy, the Magic Formula investing framework, and books such as The Little Book That Beats the Market. His approach emphasizes identifying profitable businesses at attractive valuations.
4. What does Jim Farley do at Ford?
Farley leads Ford’s overall business strategy and operations as CEO. His responsibilities include guiding the company’s response to competition, technological change, customer expectations, and the financial demands of automotive manufacturing.
5. What is the Magic Formula investing strategy?
The Magic Formula is an investment framework that ranks companies using measures associated with earnings yield and return on capital. Its goal is to identify businesses that combine attractive valuations with strong operating economics.
It is a screening approach rather than a guarantee of future investment performance.
6. How can Joel Greenblatt’s investing principles be applied to Ford?
Investors can examine Ford’s profitability, capital efficiency, valuation, financial obligations, and competitive position. They should also evaluate whether the company’s strategic investments are likely to generate acceptable returns over time.
7. Does a successful CEO automatically make a stock a good investment?
No. Management quality is only one part of an investment decision. The price paid for the stock, future earnings, financial risks, and market expectations also influence potential returns.
8. Why is capital allocation important for automakers?
Automakers must invest heavily in manufacturing, product development, technology, and supply chains. Capital allocation determines how these resources are distributed and whether the resulting investments support long-term profitability.
9. What can entrepreneurs learn from comparing an investor and a CEO?
Entrepreneurs can learn to evaluate both the economics of a business and the execution of its strategy. Strong products and capable leadership matter, but sustainable performance also depends on cost control, capital efficiency, customer demand, and sound financial decisions.
10. Why are Joel Greenblatt and Jim Farley relevant to discussions about business value?
Their careers illustrate different sides of the same broad subject. Greenblatt focuses on assessing investment value, while Farley’s role involves decisions that influence a company’s operating performance. Together, their professional perspectives provide a useful framework for understanding the relationship between management, profitability, and valuation.
Conclusion
Joel Greenblatt and Jim Farley represent two distinct approaches to understanding business success. Greenblatt’s investment philosophy emphasizes the relationship between business quality and purchase price, while Farley’s leadership at Ford highlights the operational challenges involved in managing a major automaker through industry change.
The most useful lesson from comparing their careers is that business value depends on more than reputation, ambition, or financial ratios alone. Investors need to understand what a company earns and what its shares cost, while executives must make decisions that support competitiveness, efficient operations, and sustainable financial performance.
For readers interested in value investing, corporate leadership, and the future of the automotive industry, these perspectives offer a practical starting point for evaluating how businesses create—and maintain—long-term value.
1 thought on “Joel Greenblatt and Jim Farley Two Different Approaches to Building Business Value”
Comments are closed.